


Raenest is launching a stablecoin vault for eligible customers to access a variable yield of up to 7% APY on their USDC and USDT balances. Check it out here.
If you missed Friday’s Notadeepdive, catch up here.
TOGETHER WITH CREDIT DIRECT
This term, Credit Direct Checkout is going all the way with you.
Get up to N1,000,000 to purchase iPads, laptops and other school essentials from over 500 merchants.
The proactive bank
In the same way the British talk about the weather as a safe icebreaker, a certain kind of Nigerian professional will, unprompted, tell you how disappointing their bank is.
Said Nigerian is usually a middle-class professional who earns a salary or the owner of a small business that is doing okay.
They've had the same bank account for years, perhaps a decade, and their bank has watched every salary alert and every school-fees payment leave the account in September. It knows, better than they do, when cash flow is tight and when the good times are rolling.
And what does the bank do with all this intimate, decade-long, practically marital knowledge of their financial life? It sends them a birthday text (and may sometimes get the date wrong!) and charges them for the debit alerts.
This genre of complaint follows the logic that if my bank has all this data on me, why is it never proactive?
Why doesn’t it offer me a loan before I have to ask, flag an investment when one comes along, or play some role in my financial life beyond warehousing my money and charging these pesky fees?
People who work in financial institutions respond to these complaints with a small, tired smile, because the banks are proactive.
They call customers unprompted to offer credit and discuss portfolio opportunities. They say "we noticed you have some idle balances; have you considered this exotic financial instrument..."
The caveat, of course, is that they only do it for their high-net-worth customers. This is, more or less, private banking/priority banking or whatever the bank calls the tier of account above yours.
The complaint, translated, is not really "banks are not proactive." It is "I am not rich enough for my bank to be proactive about me."
Which is fair! But it frames the whole thing as a service failure, when it might be better understood as a glimpse at a product you'd have to pay for.
Anyway, UBA is being proactive. BusinessDay reports:
United Bank for Africa (UBA) is offering its customers personal loans of up to N30 million to invest in the ongoing Dangote Petroleum Refinery initial public offering (IPO)… The offer was disclosed in an email sent by the bank to its customers, highlighting the facility as a way for investors who need additional funds to participate in the IPO.
“Want to invest in the Dangote Refinery IPO but need extra funds? Get up to N30 million with the UBA Personal Loan,” the bank said.
TOGETHER WITH RAENEST
As stablecoins become a more important way for people and businesses to receive, hold, and move money across borders, Raenest is expanding what customers can do with them.
Raenest Stablecoin Vault gives eligible customers access to variable yield of up to 7% APY on their USDC and USDT balances. APY is variable and subject to market conditions.
You can create dedicated USDC and USDT wallets; send stablecoins across supported networks; convert them to USD, GBP, EUR, NGN, and other local currencies; and spend directly from your stablecoin balances using the Raenest USD card.
For global earners, freelancers, entrepreneurs, and businesses, these capabilities provide greater flexibility in managing internationally earned money, from receiving and holding stablecoins to sending, spending, converting, and growing their balances.
Raenest serves more than one million users across 50+ countries, providing multicurrency accounts, international payments, cards, stablecoins, and investment products through a single global financial platform.
Anyway, when you click through to the details of UBA’s loan, here’s what you find:
Maximum loan amount of ₦30 million and minimum of ₦200,000 … convenient repayment period of 60 months … one-off management fee of 1%. Requirements: a functional savings or current salary account with UBA; employer on the bank’s approved organisations list; confirmed staff of your organisation; maximum borrowing up to 60% of your debt service ratio.
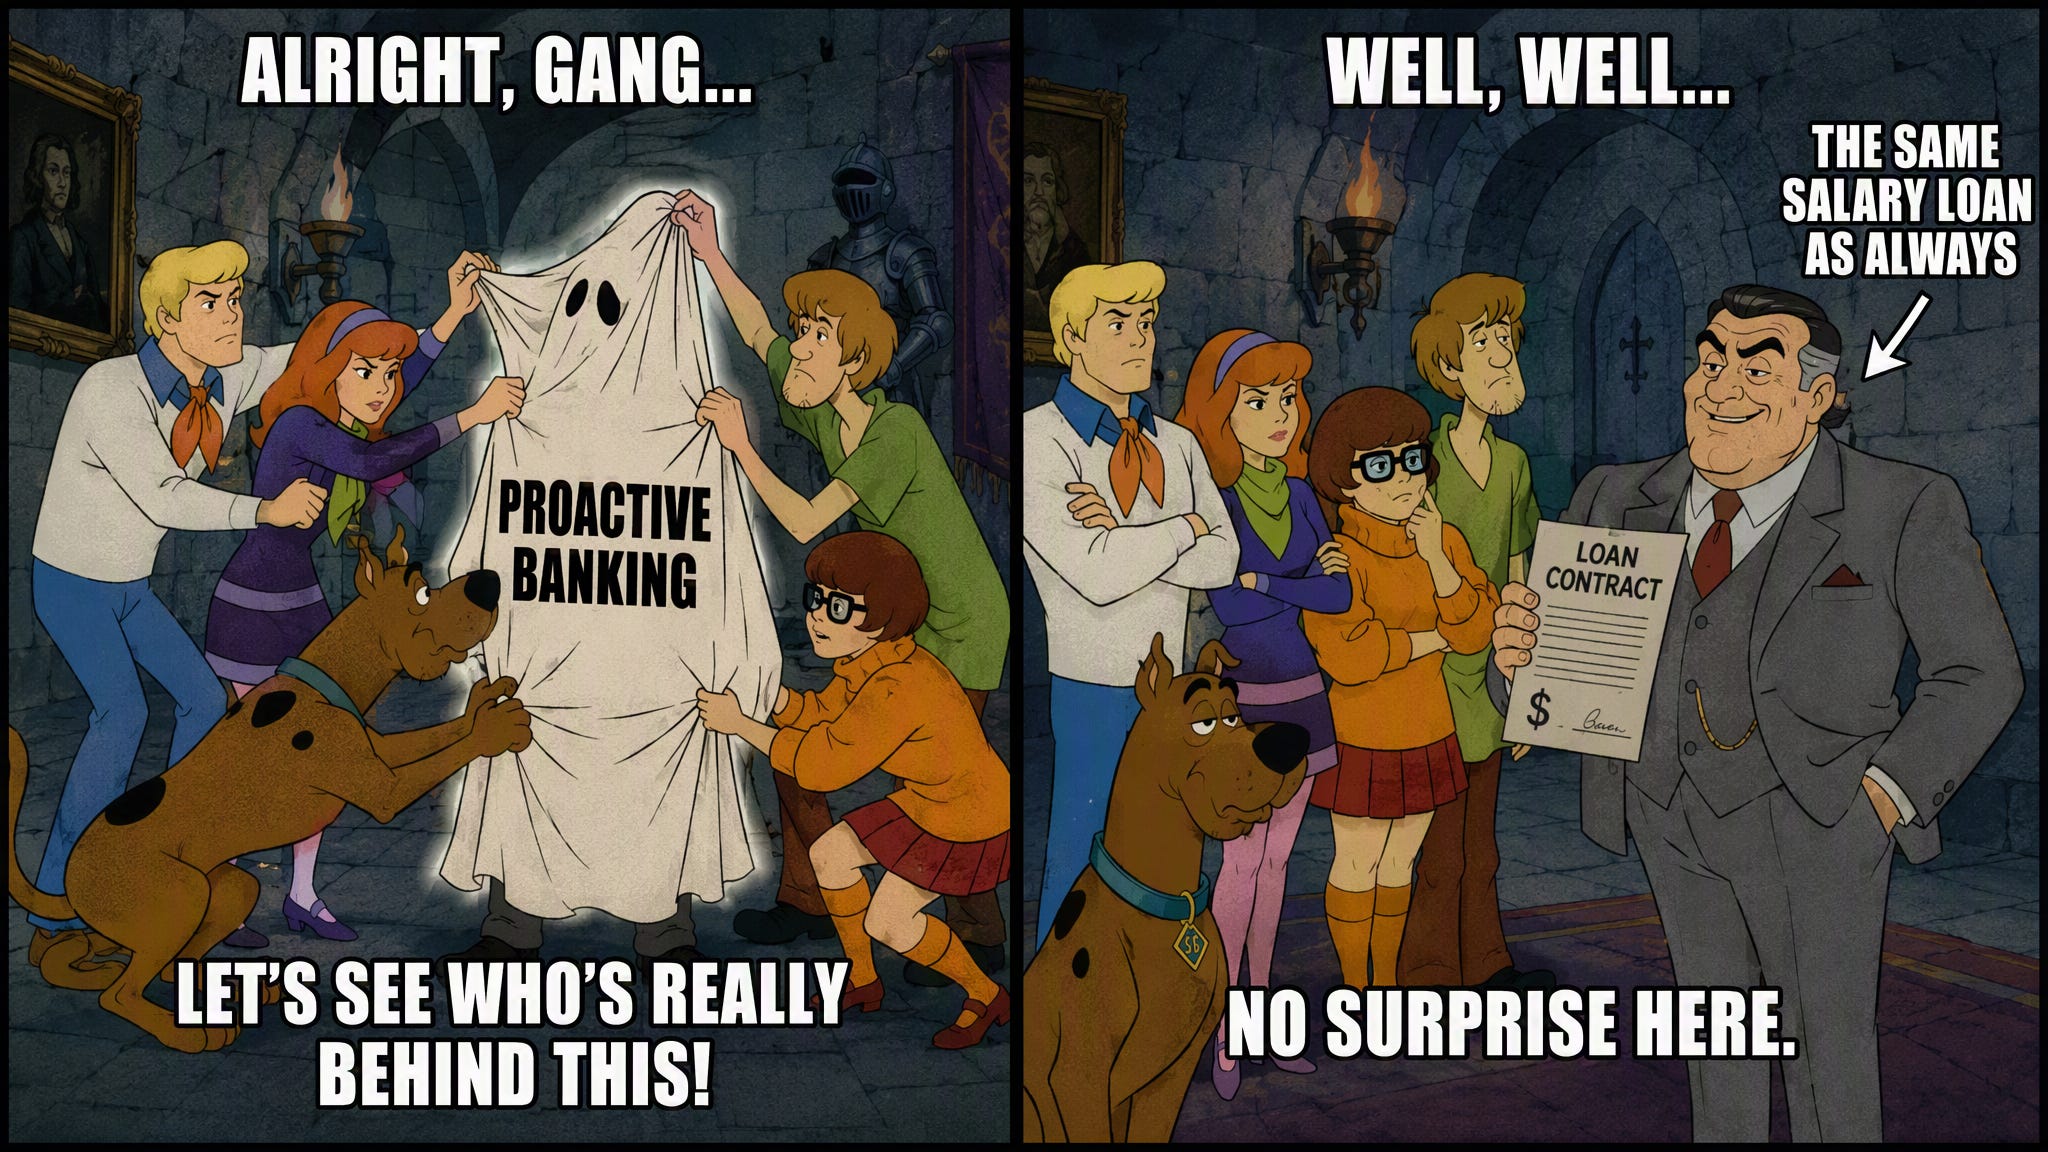
It's pretty much a personal loan secured against your salary rather than the shares. Your qualification will depend on your salary and credit history as usual, so this isn’t the proactive/innovative offering UBA has made it out to be.
The bank was always willing to lend you this money; the IPO is just this month's costume.